On October 14, 2026, the National Bureau of Statistics of the People’s Republic of China released the Consumer Price Index (CPI) and the Producer Price Index (PPI) for September 2026. The CPI rose by 0.9% year-on-year, below the market expectation of 1%; while the PPI increased by 5.0% year-on-year, expanding by 1.2 percentage points compared to the previous month. Although industrial prices seem to be picking up, analysts point out that this price surge is mainly driven by international oil prices and the cost of commodities, while consumer prices still show moderate increases, and China’s weak domestic demand issues have not disappeared.
According to Reuters on October 14, even though China’s producer prices saw the highest increase since June 2022, consumer spending remains weak, private confidence is fragile, and the economic recovery shows an imbalance with exports performing relatively stronger than domestic demand.
In September, the CPI rose by 0.9% year-on-year, slightly up from 0.8% in August but below the expected 1%; on a month-on-month basis, it increased by 0.2%, slower than the 0.4% in August. The core CPI, excluding food and energy prices, remained at 1% year-on-year, unchanged from the previous month.
Analyzing the price components, food prices in September decreased by 1.7% year-on-year, while non-food prices rose by 1.5%. Gasoline prices increased by 16.6% year-on-year, contributing about 0.47 percentage points to the CPI. The rise in energy prices supported overall inflation significantly, but after excluding food and energy, the core CPI remained at 1%, indicating limited momentum in overall consumer price growth.
Before the data release, the market generally anticipated a 1% year-on-year increase in the CPI for September but the actual figures fell short of expectations.
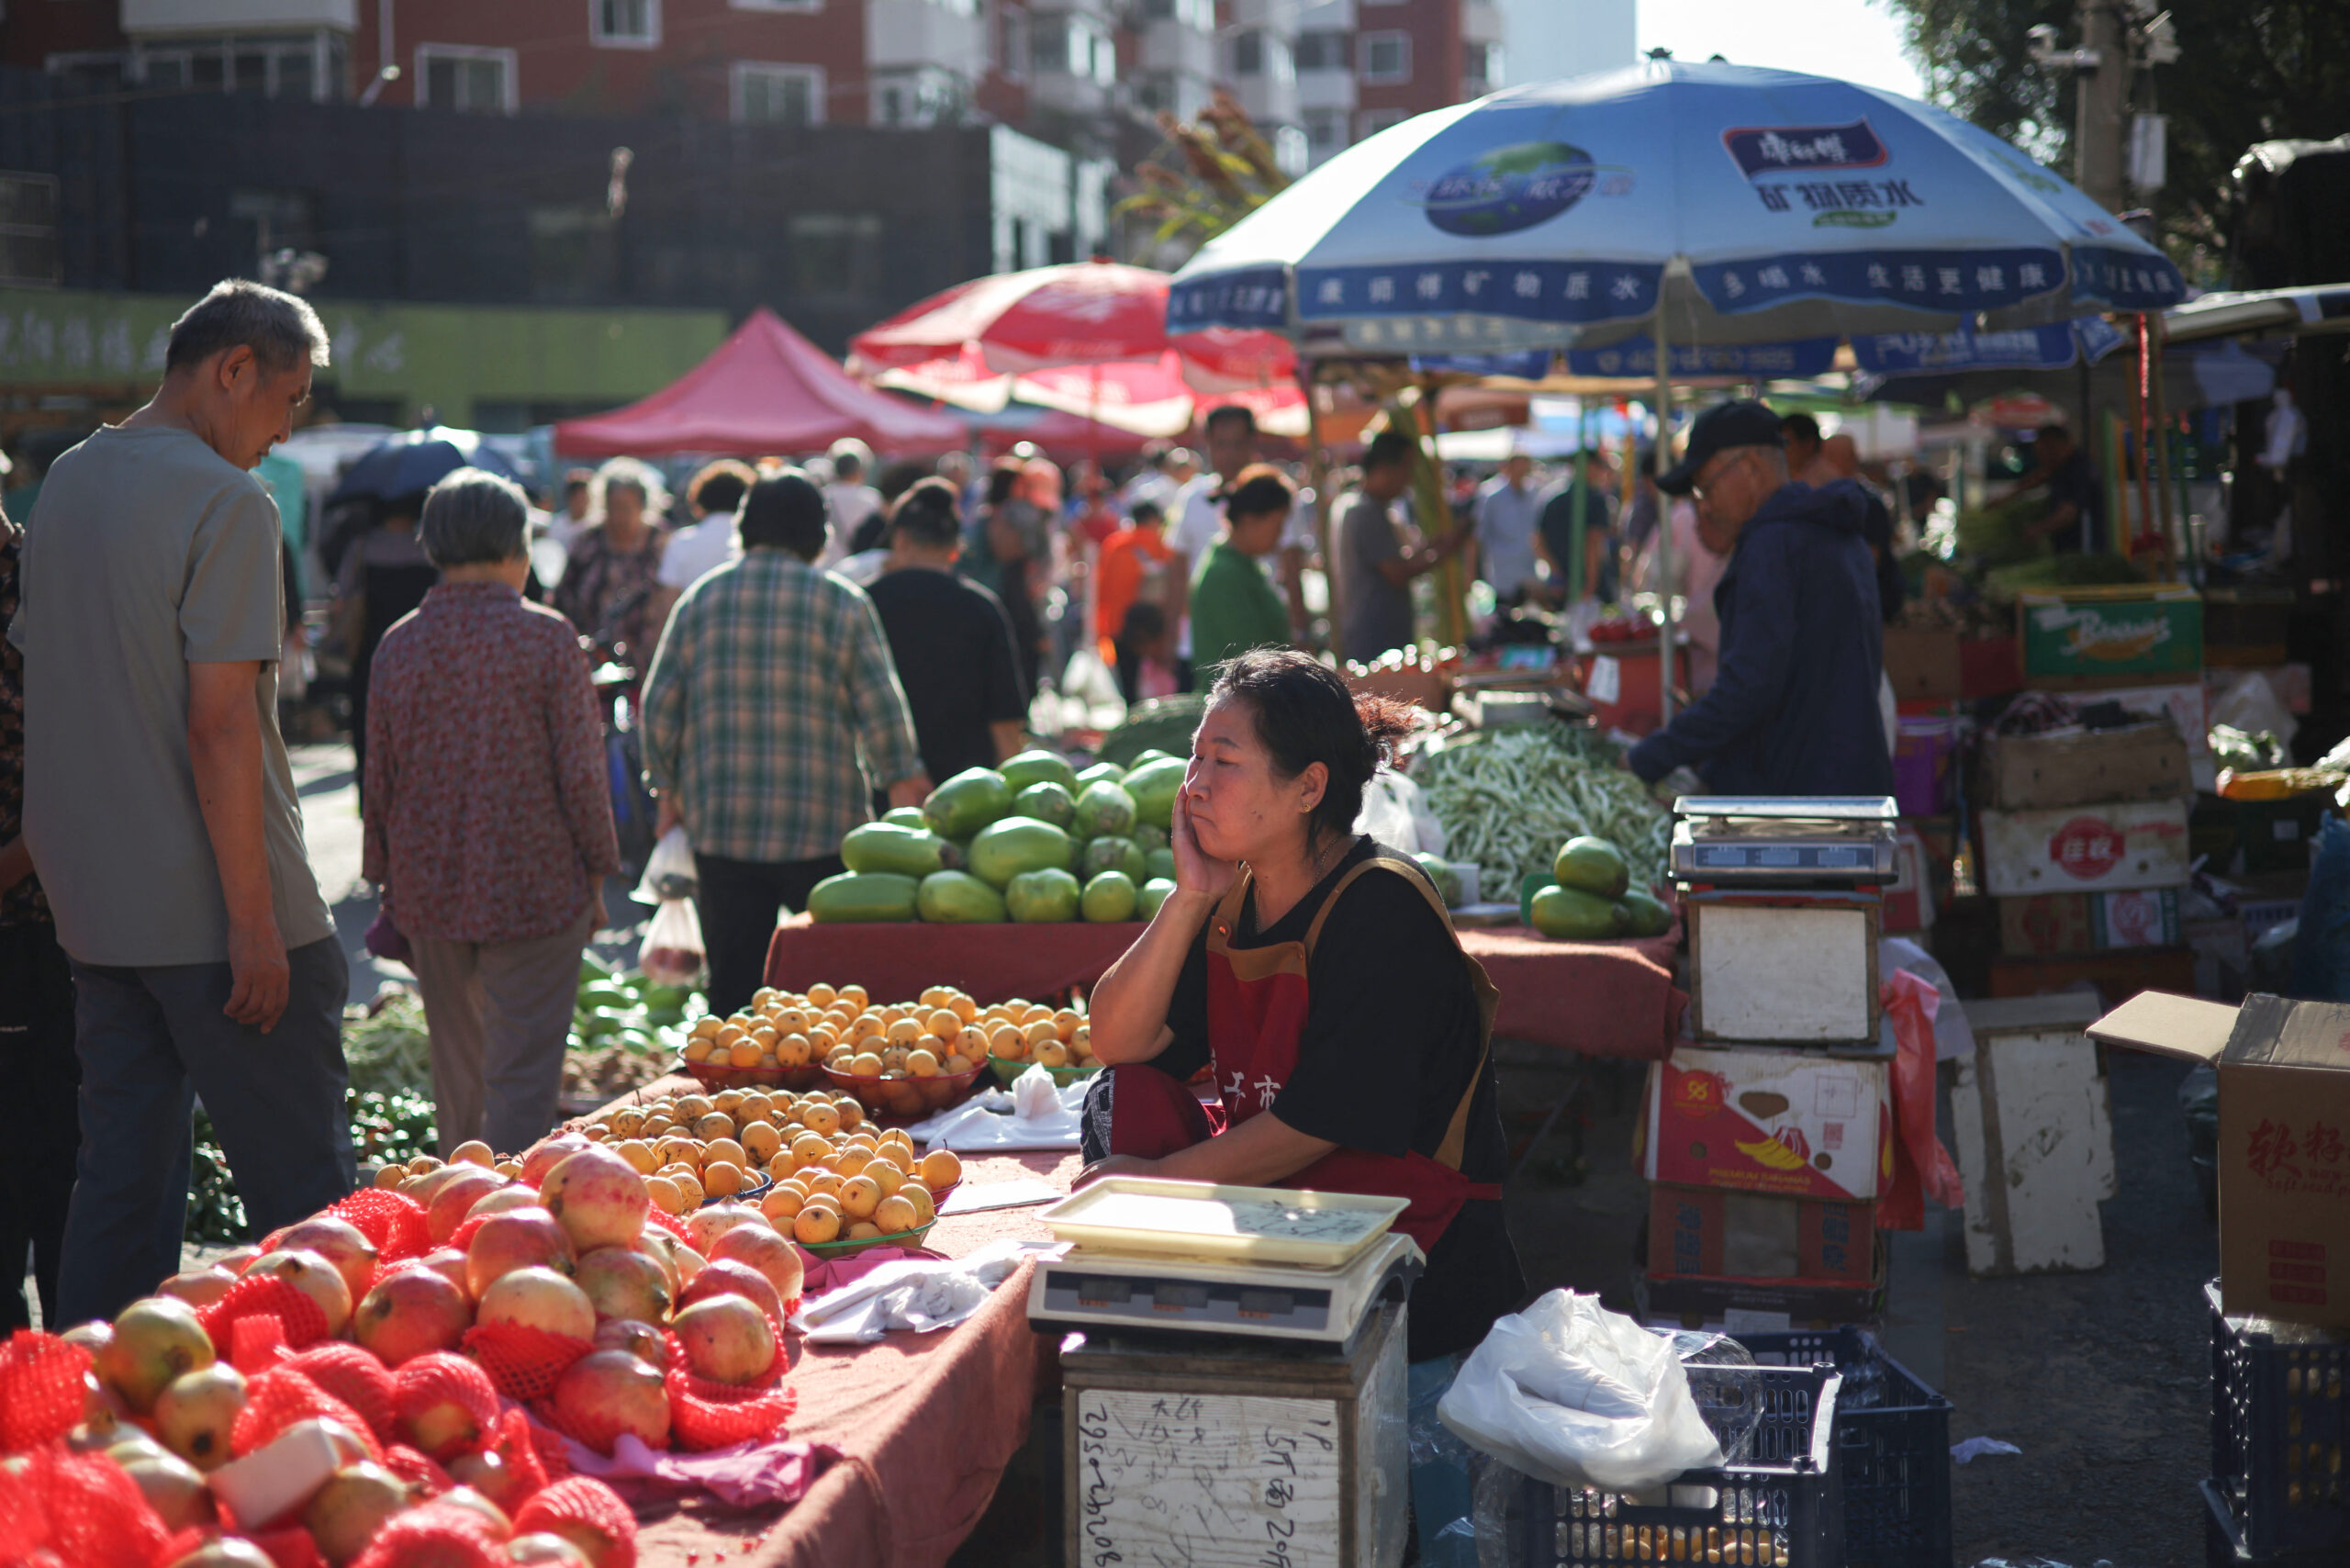
Reuters reported that household spending remains subdued, with consumers showing cautious spending behavior, indicating that the slight rise in price indices is not enough to prove a widespread and sustained improvement in domestic demand.
In September, the PPI increased by 5.0% year-on-year, higher than August’s 3.8% and surpassing the economists’ estimated 4.5%; on a month-on-month basis, it rose by 1.2%, expanding by 0.8 percentage points from the previous month. While industrial prices are rising rapidly, the underlying reasons for the price increases, beyond just industrial demand recovery, warrant closer attention.
According to Reuters, Nguyen Hoang Nam, an economist at Capital Economics in China, pointed out that the significant upward pressure on prices stems largely from disruptions in commodity supplies due to conflicts in the Middle East. Industries such as fuel processing, chemicals, and non-ferrous metals have seen significant price hikes. The rise in international oil and raw material costs has increased manufacturers’ production costs; however, due to weak demand, the transmission of costs to end consumer prices is limited.
Official data also shows that in September, prices in coal mining and washing rose by 35.3% year-on-year, oil and gas extraction increased by 24.5%, petroleum, coal, and fuel processing industries increased by 21.6%, chemical materials and chemical products manufacturing rose by 12.1%. The price increases in these industries are closely related to changes in energy and raw material costs and may not directly correlate with synchronized growth in end-demand.
Furthermore, the expansion in PPI has not led to a significant spike in CPI. While industrial prices are rising quickly, core consumer inflation is staying at 1%, highlighting the asynchrony between cost pressures and consumer demand.
Reuters emphasizes that household spending in China is still weak, private confidence is fragile, and the economic recovery remains uneven, with exports performing better than domestic consumption. Zhou Hao, Chief Economist at China CITIC Bank International, noted that the key going forward is whether industrial activity can translate into employment, income growth, and consumer confidence; if this transmission mechanism fails to improve, the gap between industrial and consumer prices will be difficult to narrow from the demand side.
Therefore, although the September PPI climbed to 5%, reflecting a faster rise in industrial prices, it includes cost pressures from international energy and raw material supply fluctuations. If consumer demand does not improve concurrently, industrial price hikes may not necessarily translate into overall growth in enterprise sales, profits, and household incomes.
From the lower-than-expected CPI, maintaining low core inflation, to the PPI being mainly driven by energy and commodity prices, the data presented in September is not simply a story of “price recovery” but a scenario where rising industrial costs coexist with weak end-demand. Assessing the true recovery of the Chinese economy will require monitoring indicators such as household consumption, employment, income, actual business demand, rather than solely focusing on the expanding PPI.