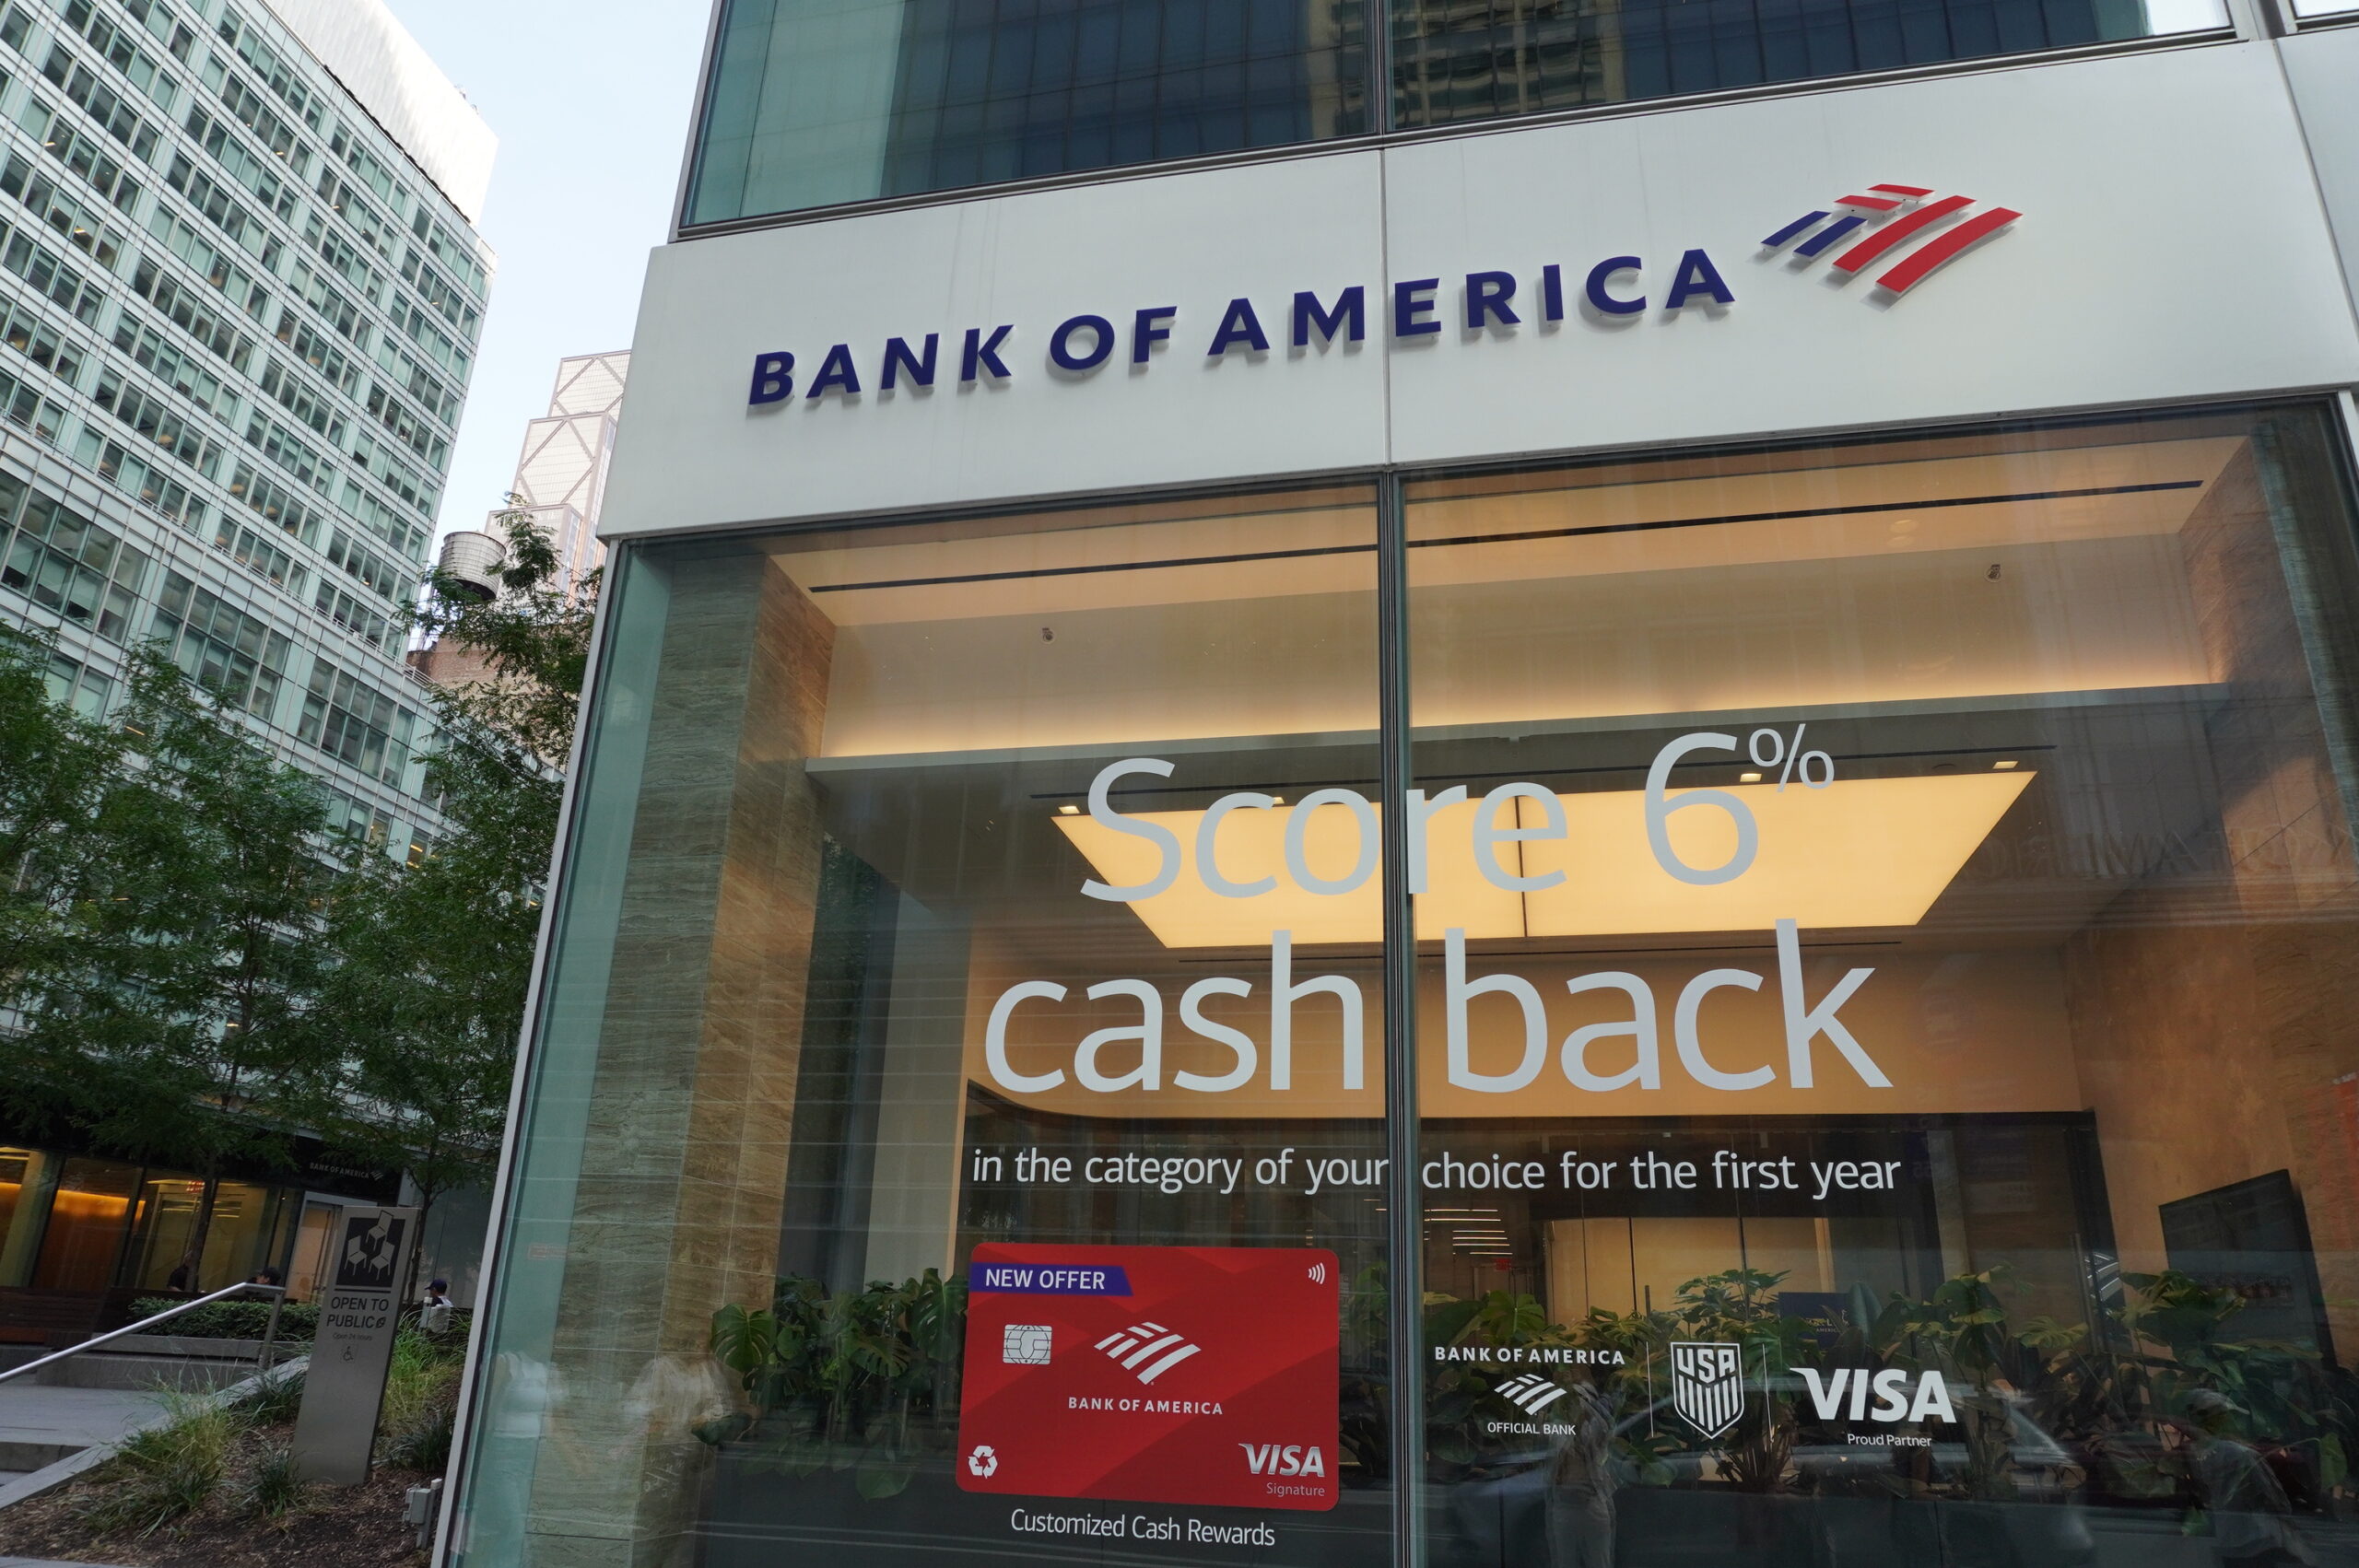
On October 14, 2026, Bank of America was fined $1.21 billion by U.S. regulators for its failure to address long-standing issues in anti-money laundering. The regulatory authorities stated that the second largest bank in the United States had failed to report suspicious transactions exceeding $5 billion.
According to a press release from the U.S. Department of the Treasury on Tuesday, this fine is the third largest ever imposed by the department. The reason behind the penalty was Bank of America’s failure to report over $5 billion in suspicious transactions to the government, of which $1 billion posed risks to U.S. national security and other high-priority matters, including money laundering networks related to China (the CCP) and activities along the U.S. Southwest border.
U.S. Treasury Secretary Scott Bessent mentioned in a statement, “Financial institutions are at the forefront of protecting our economic security and national security. When a bank of this magnitude fails to fulfill its obligations in anti-money laundering and sanctions, the consequences extend far beyond its own scope, exposing the entire U.S. financial system to significant illicit financial risks.”
The Treasury Department stated that the bank prioritized its own revenue when formulating its compliance plans, excessively relying on external investigations by law enforcement agencies and other financial institutions rather than relying on its internal controls.
As part of the settlement agreement, Bank of America admitted to failing to implement an anti-money laundering compliance plan and conduct necessary due diligence on foreign correspondent bank accounts, thereby intentionally violating the Bank Secrecy Act.
Under the consent order, Bank of America must appoint an independent third party to review past transactions, identify suspicious activities that the bank failed to detect at the time, and submit reports to FinCEN, the Financial Crimes Enforcement Network of the Treasury Department.
A spokesperson for Bank of America stated, “Financial crime compliance issues are serious, and we have a responsibility to do this work well. We have invested billions of dollars in technology and deployed thousands of employees in our fight against financial crime. Our team has made significant progress and is committed to completing the necessary work to address the issues raised by regulators.”
The spokesperson added that the bank will release its third-quarter earnings report on Wednesday, which will include a non-tax deductible charge of $1.2 billion, resulting in a decrease of approximately 17 cents in the bank’s earnings per share for the quarter.
Following this news, Bank of America’s stock price fell 1.1% at the close of trading on Tuesday and dropped by 2.7% in after-hours trading.
(Reuters contributed to this article)