
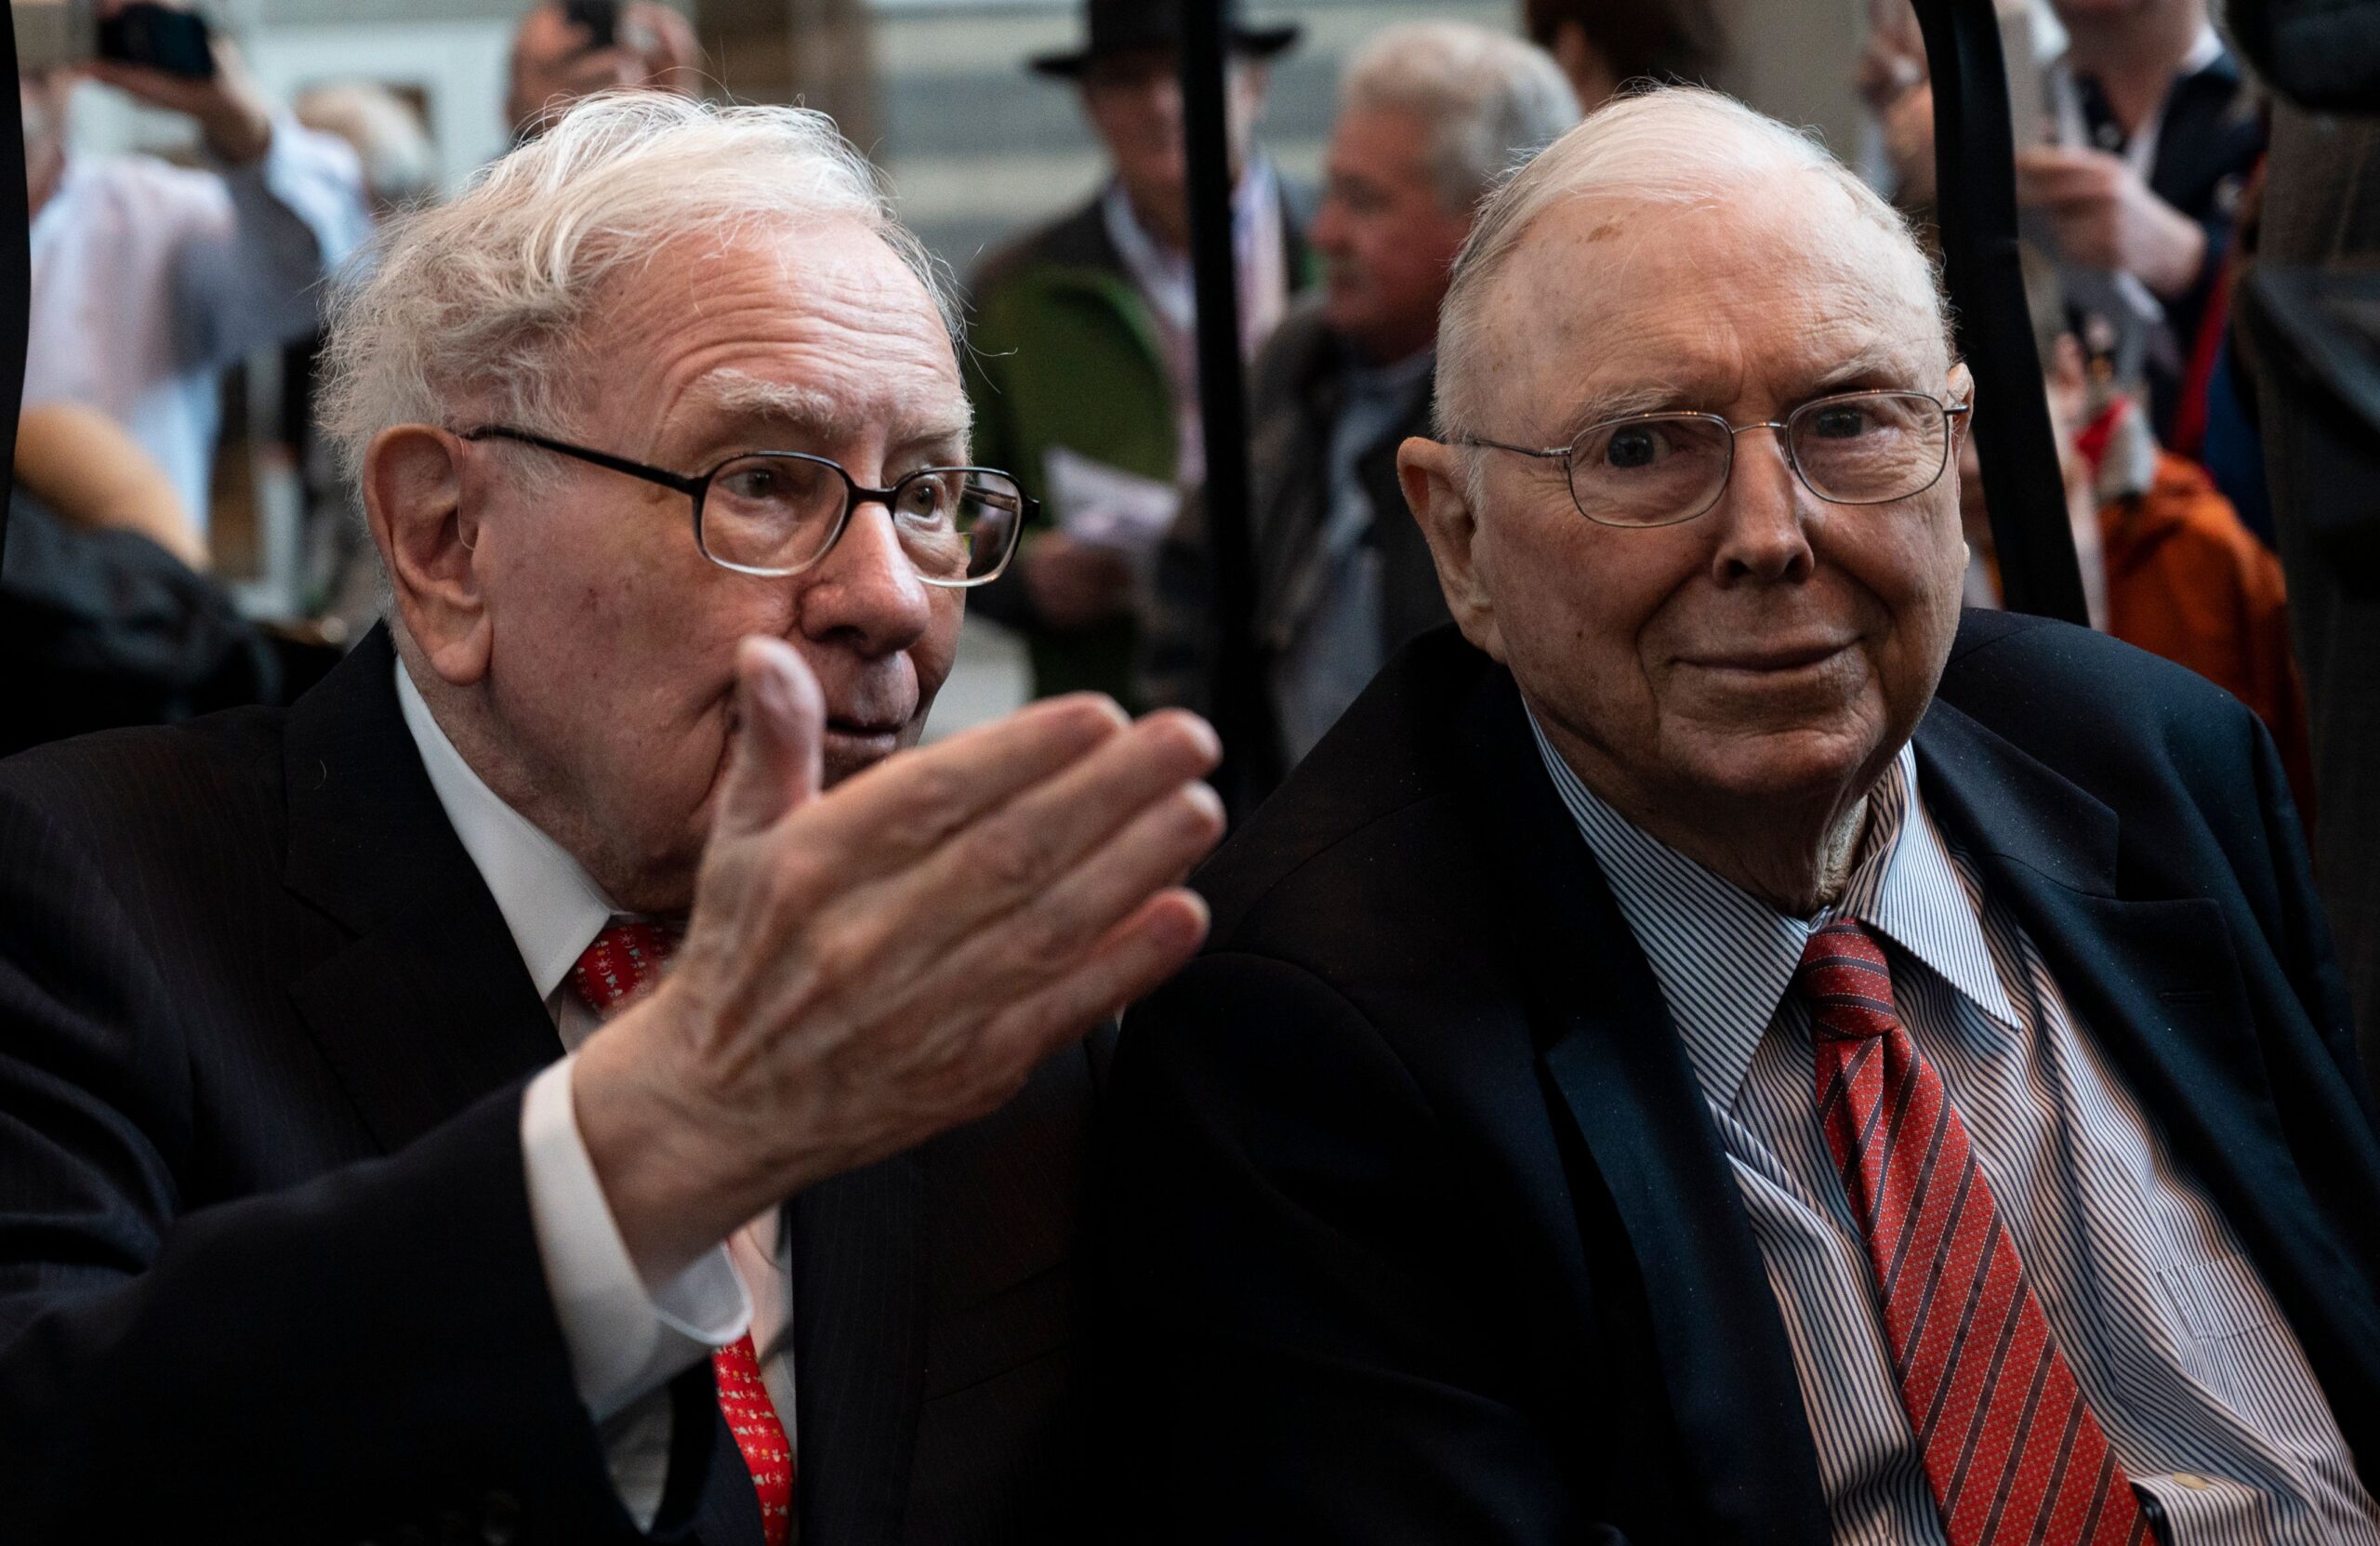
The late vice chairman of Berkshire Hathaway, Charlie Munger, had emphasized multiple times that wealth comes from holding appreciating assets for the long term, and this includes knowledge. Munger passed away in November 2023 at the age of 99. From his speeches at shareholders’ meetings and public lectures, it can be inferred that he believed in five types of assets worth long-term investment.
Munger delved into psychology, history, economics, biology, and physics, and distilled the core concepts of these disciplines into what he called a “latticework of mental models”. He often said that a person who only has a hammer sees everything as a nail, meaning that individuals who only understand a single field are prone to fitting all problems into their familiar framework.
In “Poor Charlie’s Almanack,” Munger wrote that the wise people he encountered in his lifetime were all avid readers. He also mentioned that his children teased him, calling him a walking book with two legs.
Warren Buffett initially preferred to buy undervalued, mediocre companies, which he referred to as “cigar butts,” likening them to picking up a discarded cigarette butt with one last puff left.
In his 2014 shareholder letter, Buffett wrote that Munger’s blueprint for him was to stop buying ordinary businesses at extremely low prices and instead invest in excellent businesses at reasonable prices. Excellent businesses typically possess competitive advantages, high return on capital, and the ability to increase prices without losing customers.
A widely circulated phrase often attributed to Munger is, “The big money is not in the buying and selling but in the waiting.”
Although Munger amassed his wealth by holding a concentrated portfolio of a few stocks, he openly stated that index funds are more suitable for most people.
At the 2019 Daily Journal annual meeting in February, Munger stated that index funds had essentially outperformed everyone. At the 2023 meeting, he criticized active fund managers for charging high fees without benefiting their clients, describing it as a “profound moral failure.” He further mentioned that buying and holding index funds long-term is the “best default option.”
When evaluating assets, Munger emphasized the importance of how much capital can be earned back. In a speech at the University of Southern California Business School in 1994, he pointed out that over the long term, stock returns are unlikely to greatly exceed a company’s return on capital. He illustrated that a company with a 6% return on capital, regardless of initially purchasing it at a significant discount, would not differ significantly in return after holding it for 40 years. Conversely, a company that maintains an 18% return on capital for two to three decades, even if the initial purchase price seems high, would yield a considerable return in the end.
Munger frequently stresses the concept of a “circle of competence,” advocating that major decisions should fall within one’s true understanding. In a speech at the University of Southern California Gould School of Law graduation ceremony in May 2007, he mentioned how he often observed individuals steadily progressing in life, not necessarily the smartest or hardest working, but they were “learning machines,” becoming a bit wiser every night before going to bed compared to when they woke up in the morning.