
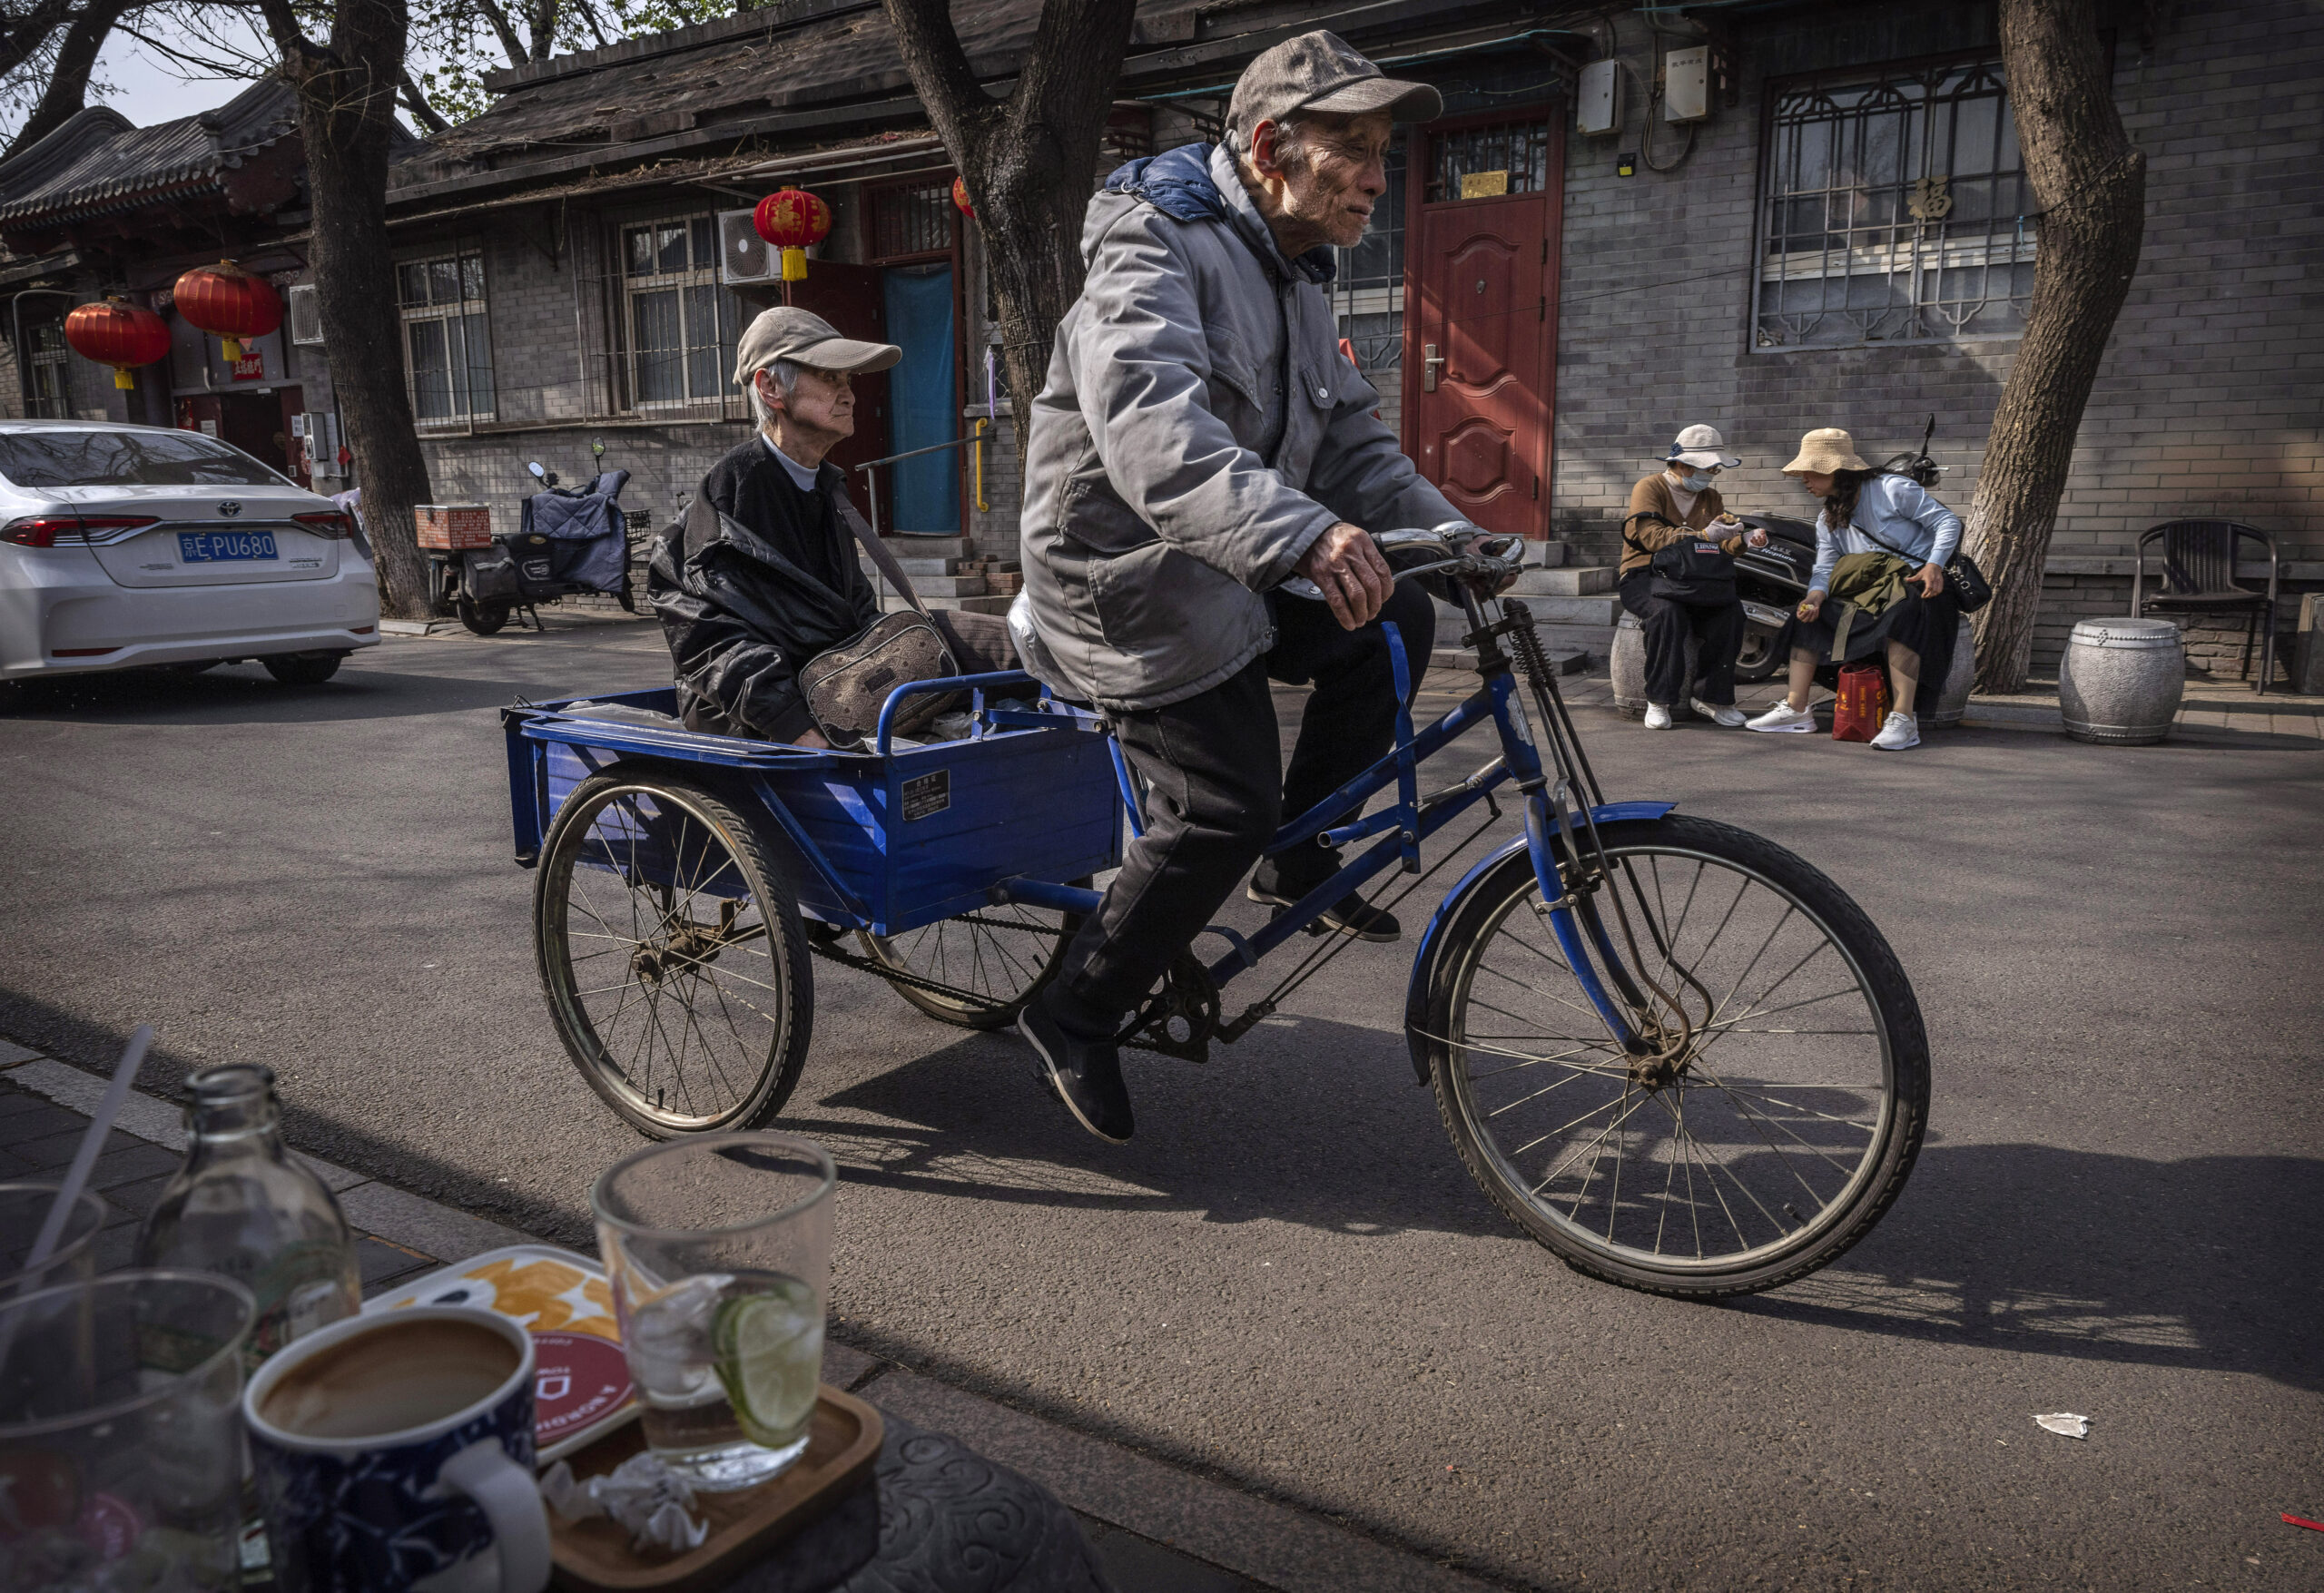
The aging population in Beijing is accelerating, with official data showing that as of the end of 2025, the population aged 60 and above accounted for 24.3% of the city’s permanent residents. It is projected that by 2035, this percentage will exceed 33%, meaning one out of every three residents will be elderly.
This demographic shift in Beijing reflects the population and economic pressures facing China as a whole. China’s population has been declining since 2022, with a shrinking workforce and a growing number of retirees. A study by the International Monetary Fund (IMF) indicates that population aging will not only drag down economic growth but also lead to an increase in pension expenditures. Disparities in the urban-rural social security system pose another major concern.
On Monday, Reuters cited an article from the Beijing Daily reporting on this projection. The relevant data was released at the 2026 “Si Ji Qing Forum” held recently. The forum noted that as a megacity, Beijing’s aging process is accelerating, with the city’s population aged 60 and above reaching 5.288 million by the end of 2025, accounting for 24.3% of the permanent residents. By 2035, Beijing is expected to enter a stage of severe population aging, with the elderly population exceeding 33%.
Reuters also estimated that the Chinese authorities may need to bear around 180 billion yuan (approximately 26.92 billion US dollars) in total costs this year to encourage childbirth.
A working paper released by the IMF in February this year titled “China’s Population Aging and Pension Reform” predicts that China’s workforce aged 20 to 60 is expected to decrease from about 840 million in 2024 to 614 million in 2050, a decrease of over 226 million, representing a reduction of more than a quarter. The decrease in workforce will also weaken capital accumulation.
The research model estimates that without retirement age reforms, by 2050, population aging could lead to a nearly 2-percentage-point decrease in China’s annual real GDP growth rate.
As the retired population increases, the fiscal pressure on pension funds is also mounting. The IMF study mentioned that without raising the retirement age, China’s pension expenditure as a percentage of GDP could rise from the initial 5.4% in the model to 15.3% by 2050; even with reforms, it could still reach 11.9% in 2050.
Apart from expenditure growth, the unequal distribution of social security benefits is also a point of concern. The study points out that the average pension for urban workers is over 40% of China’s per capita GDP, whereas for rural residents, it is only about 3%, a tenfold difference between the two.
According to the paper, around 1.07 billion people in China were covered by public pension insurance in 2023, but only about 44% of working-age individuals were effectively participating in the wage-linked pension insurance system.
Approximately 78% of government pension subsidies were channeled to urban workers’ pension insurance. The study suggests these subsidies may have regressive effects, benefiting the middle and high-income groups more.
Insufficient pension coverage is also one of the factors contributing to weak consumption in China. Krishna Srinivasan, Director of the IMF’s Asia Pacific Department, stated in an interview with the South China Morning Post in September that China needs to improve its pension and healthcare systems to reduce households’ need for excessive savings to cover future risks.
He emphasized, “China must significantly increase fiscal spending to enhance the social security system, which will reduce households’ precautionary savings and boost consumption.”
Srinivasan pointed out that China’s economic model relying on exports and investments has reached its limits. The long-lasting downturn in the real estate market has eroded household wealth and consumer confidence.
“The biggest obstacle is the loss of confidence,” he said.
The report also noted that many rural migrant workers, holding rural household registrations but working in urban areas, are unable to enjoy the same public welfare benefits such as healthcare as local residents, potentially forcing them to maintain higher levels of savings to cope with future expenses.