
In traditional belief, 65 years old is considered a watershed for bidding farewell to the workplace and indulging in grandchildren. However, facing inflation pressure and longer life expectancy, the definition of retirement in the United States is undergoing a structural transformation. For many first-generation Chinese immigrants, retirement is no longer a complete cessation of work status but an entrance into the part-time job market through “putting down ego,” embarking on a long-term strategy that balances financial defense and mental health.
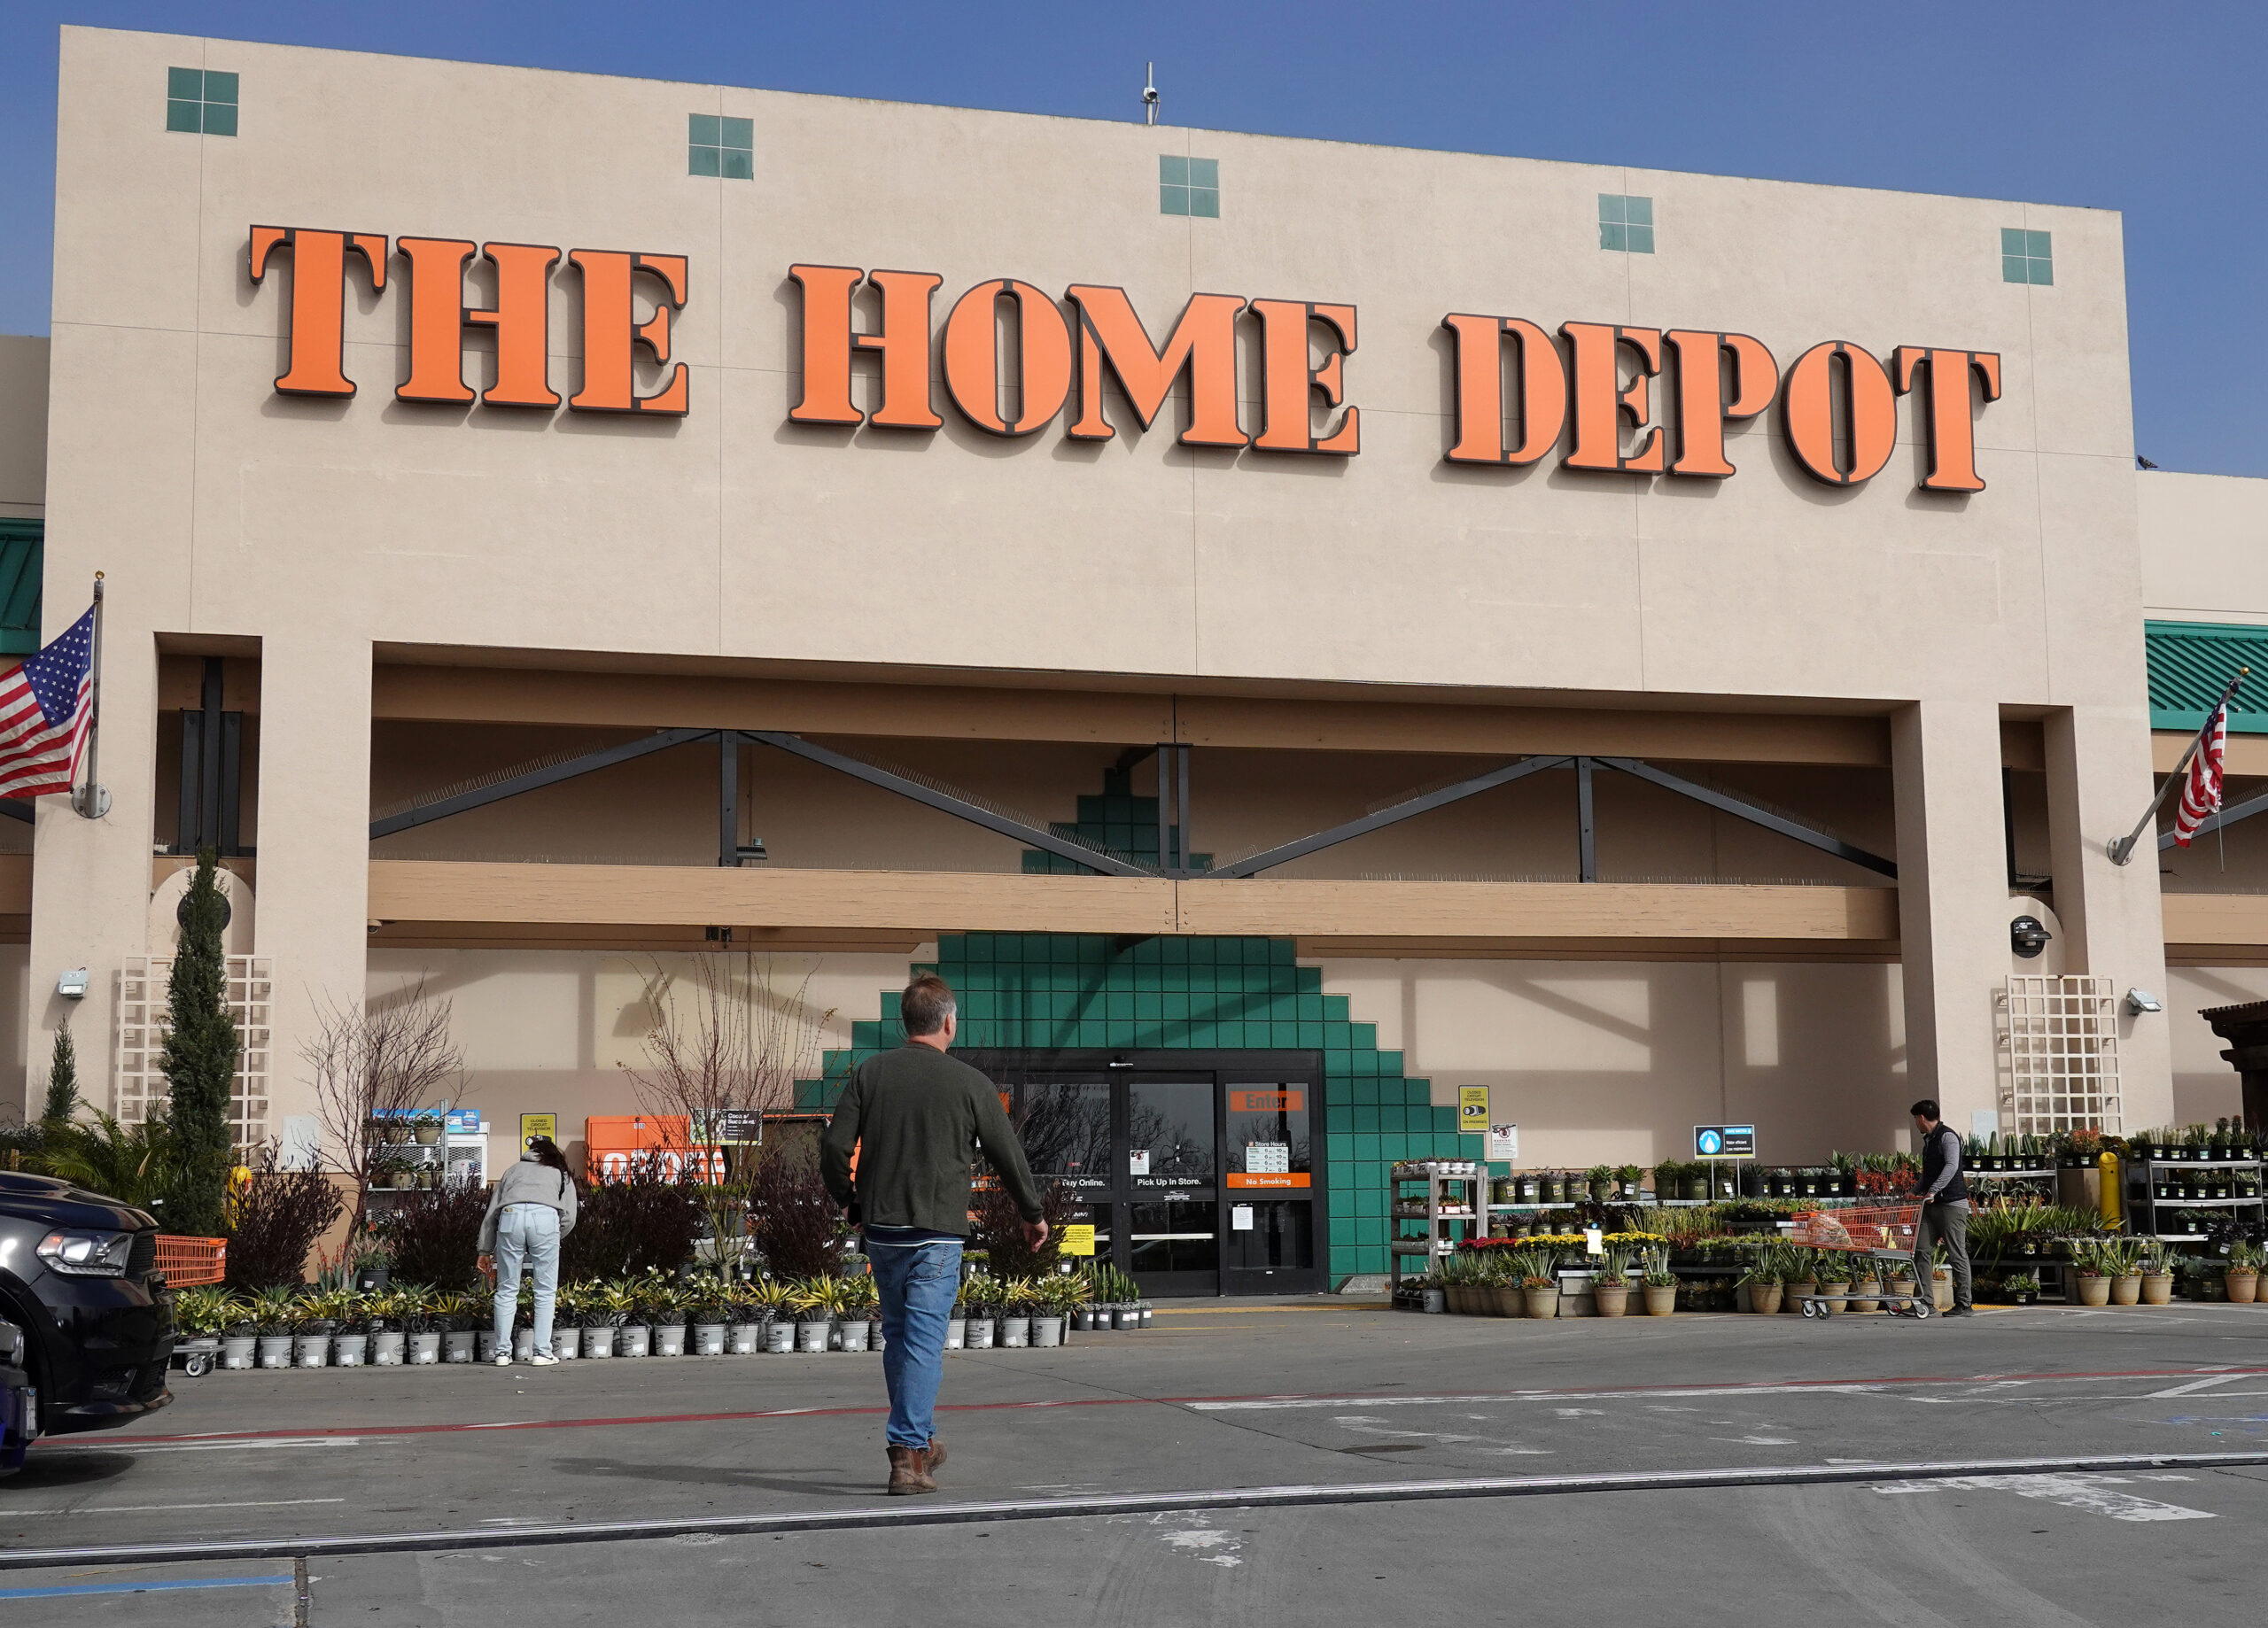
Residing in Irvine, Southern California, a 67-year-old Chinese immigrant Mr. Chen (pseudonym) and his wife retired from traditional Chinese businesses three years ago. Before retirement, he was a logistics manager, while his wife was an executive director, earning a combined income of approximately $140,000 to $160,000 annually. Now, Mr. Chen spends three and a half days a week working as a part-time hardware consultant at a Home Depot near his home, while his wife takes on a half-time clerical job at a local Chinese accounting firm, bringing in a combined part-time net income of over $1,000 per month.
The early double income allowed Mr. Chen and his wife to barely afford a townhouse in Irvine and raise their children. However, due to the high cost of living and various educational expenses in Irvine, the funds available for investment in their 401(k) after deducting taxes were quite limited. After years of hard work, the couple accumulated around $600,000 in their retirement accounts.
Although they have paid off their mortgage, facing the continuous price increases in California, their seemingly substantial retirement savings still make Mr. Chen feel like he’s walking on thin ice. “I didn’t start working because I couldn’t afford to eat,” Mr. Chen confessed. With annual property taxes over $10,000, rising house insurance premiums, and monthly homeowners association fees exceeding $400, he feels extremely anxious about the “outflow-only” state of his retirement account.
Their part-time income is just enough to cover their monthly grocery expenses and utilities. As for significant fixed expenses like property taxes and insurance, they are supported by high-yield certificates of deposit (CD Ladder) set aside from their early planning. This strategy of segregating daily expenses from large payments has become a financial cushion for their living expenses.
The key lies in the Social Security benefit calculation strategy. By maintaining daily expenses through part-time income, Mr. Chen avoids the necessity to withdraw from his 401(k) at low prices during stock market fluctuations, thus mitigating the risk of permanently reducing his principal due to selling stocks at low levels in the initial retirement years, while also delaying the receipt of Social Security benefits from the Full Retirement Age (FRA) of 67 to 70 years.
According to the regulations of the U.S. Social Security Administration, for every year delayed after the FRA, the payment amount increases by approximately 8%, and this reward increase peaks at 70 years old. “In the current market environment, where can you find a low-risk investment that guarantees an annual stable 8% growth? This part-time job is like buying me time,” cleverly calculated Mr. Chen.
However, financial experts also caution that viewing delayed payment as an “8% return” may sound intuitive, but the actual benefits depend on life expectancy. For Mr. Chen, delaying benefits from 67 to 70 years means he initially forgoes three years of Social Security benefits. Therefore, he must live past the “breakeven point” of around 82.5 years, where the additional monthly payments received after 70 years compensate for the “missed payments” of the first three years, for the total delayed payment to truly surpass the scenario of starting benefits at 67.
Mr. Chen’s choice is not exceptional but rather a trend in the U.S. labor market. According to data from the Bureau of Labor Statistics (BLS), in 2024, nearly 20% of the population aged 65 and above are still working or actively seeking jobs. In 2025, 19.1% of the 65 and older population remains in the labor market. Although this percentage has slightly decreased from the historical peak in 2019 (20.2%), it still shows a significant long-term growth trend compared to 2000 (12.9%).
This labor participation rate structure differs fundamentally from the younger generation. Among workers aged 65 and above, as high as 38.3% choose a part-time model with shorter working hours, while only 14.2% of 55 to 64-year-old workers engage in part-time work.
Looking back on history, the labor participation rate of the elderly population in the United States plummeted to around 11% in the 1980s and 1990s, hitting historical lows. Since the late 1990s, the labor participation rate has significantly rebounded and reached its peak before the 2019 pandemic; although there has been a slight decline in recent years, the overall proportion is still far higher than the historical low. The prevalence of flexible work patterns has made it easier for seniors to stay in the workforce at their pace.
For Mr. Chen, part-time work is not just a defensive cash flow strategy but a crucial piece in reshaping the structure of his retirement life. Apart from practical considerations, continuing to work is also a powerful tool for Chinese elderly to combat social isolation.
Many Chinese elderly people, once fully retired, easily fall into the anxiety of losing their sense of purpose in life due to children working in different states and lacking diverse local social circles. Part-time work forces Mr. Chen to step out of his home, maintain his English conversational skills, and interact with the community. He says, “If you stay at home watching TV every day, your brain deteriorates rapidly. Going to work now, my colleagues and clients value my experience. The feeling of being needed at work is irreplaceable by just gardening at home.”
For contemporary Chinese Americans, working in their later years is no longer a symbol of toiling labor. Through moderate part-time work, they resist inflation without tapping into their core retirement savings, maximizing Social Security benefits, and enhancing social connections. This transition of retirement from an “absolute endpoint” to a “flexible transition” is becoming a rational and responsible solution for late-life living.