
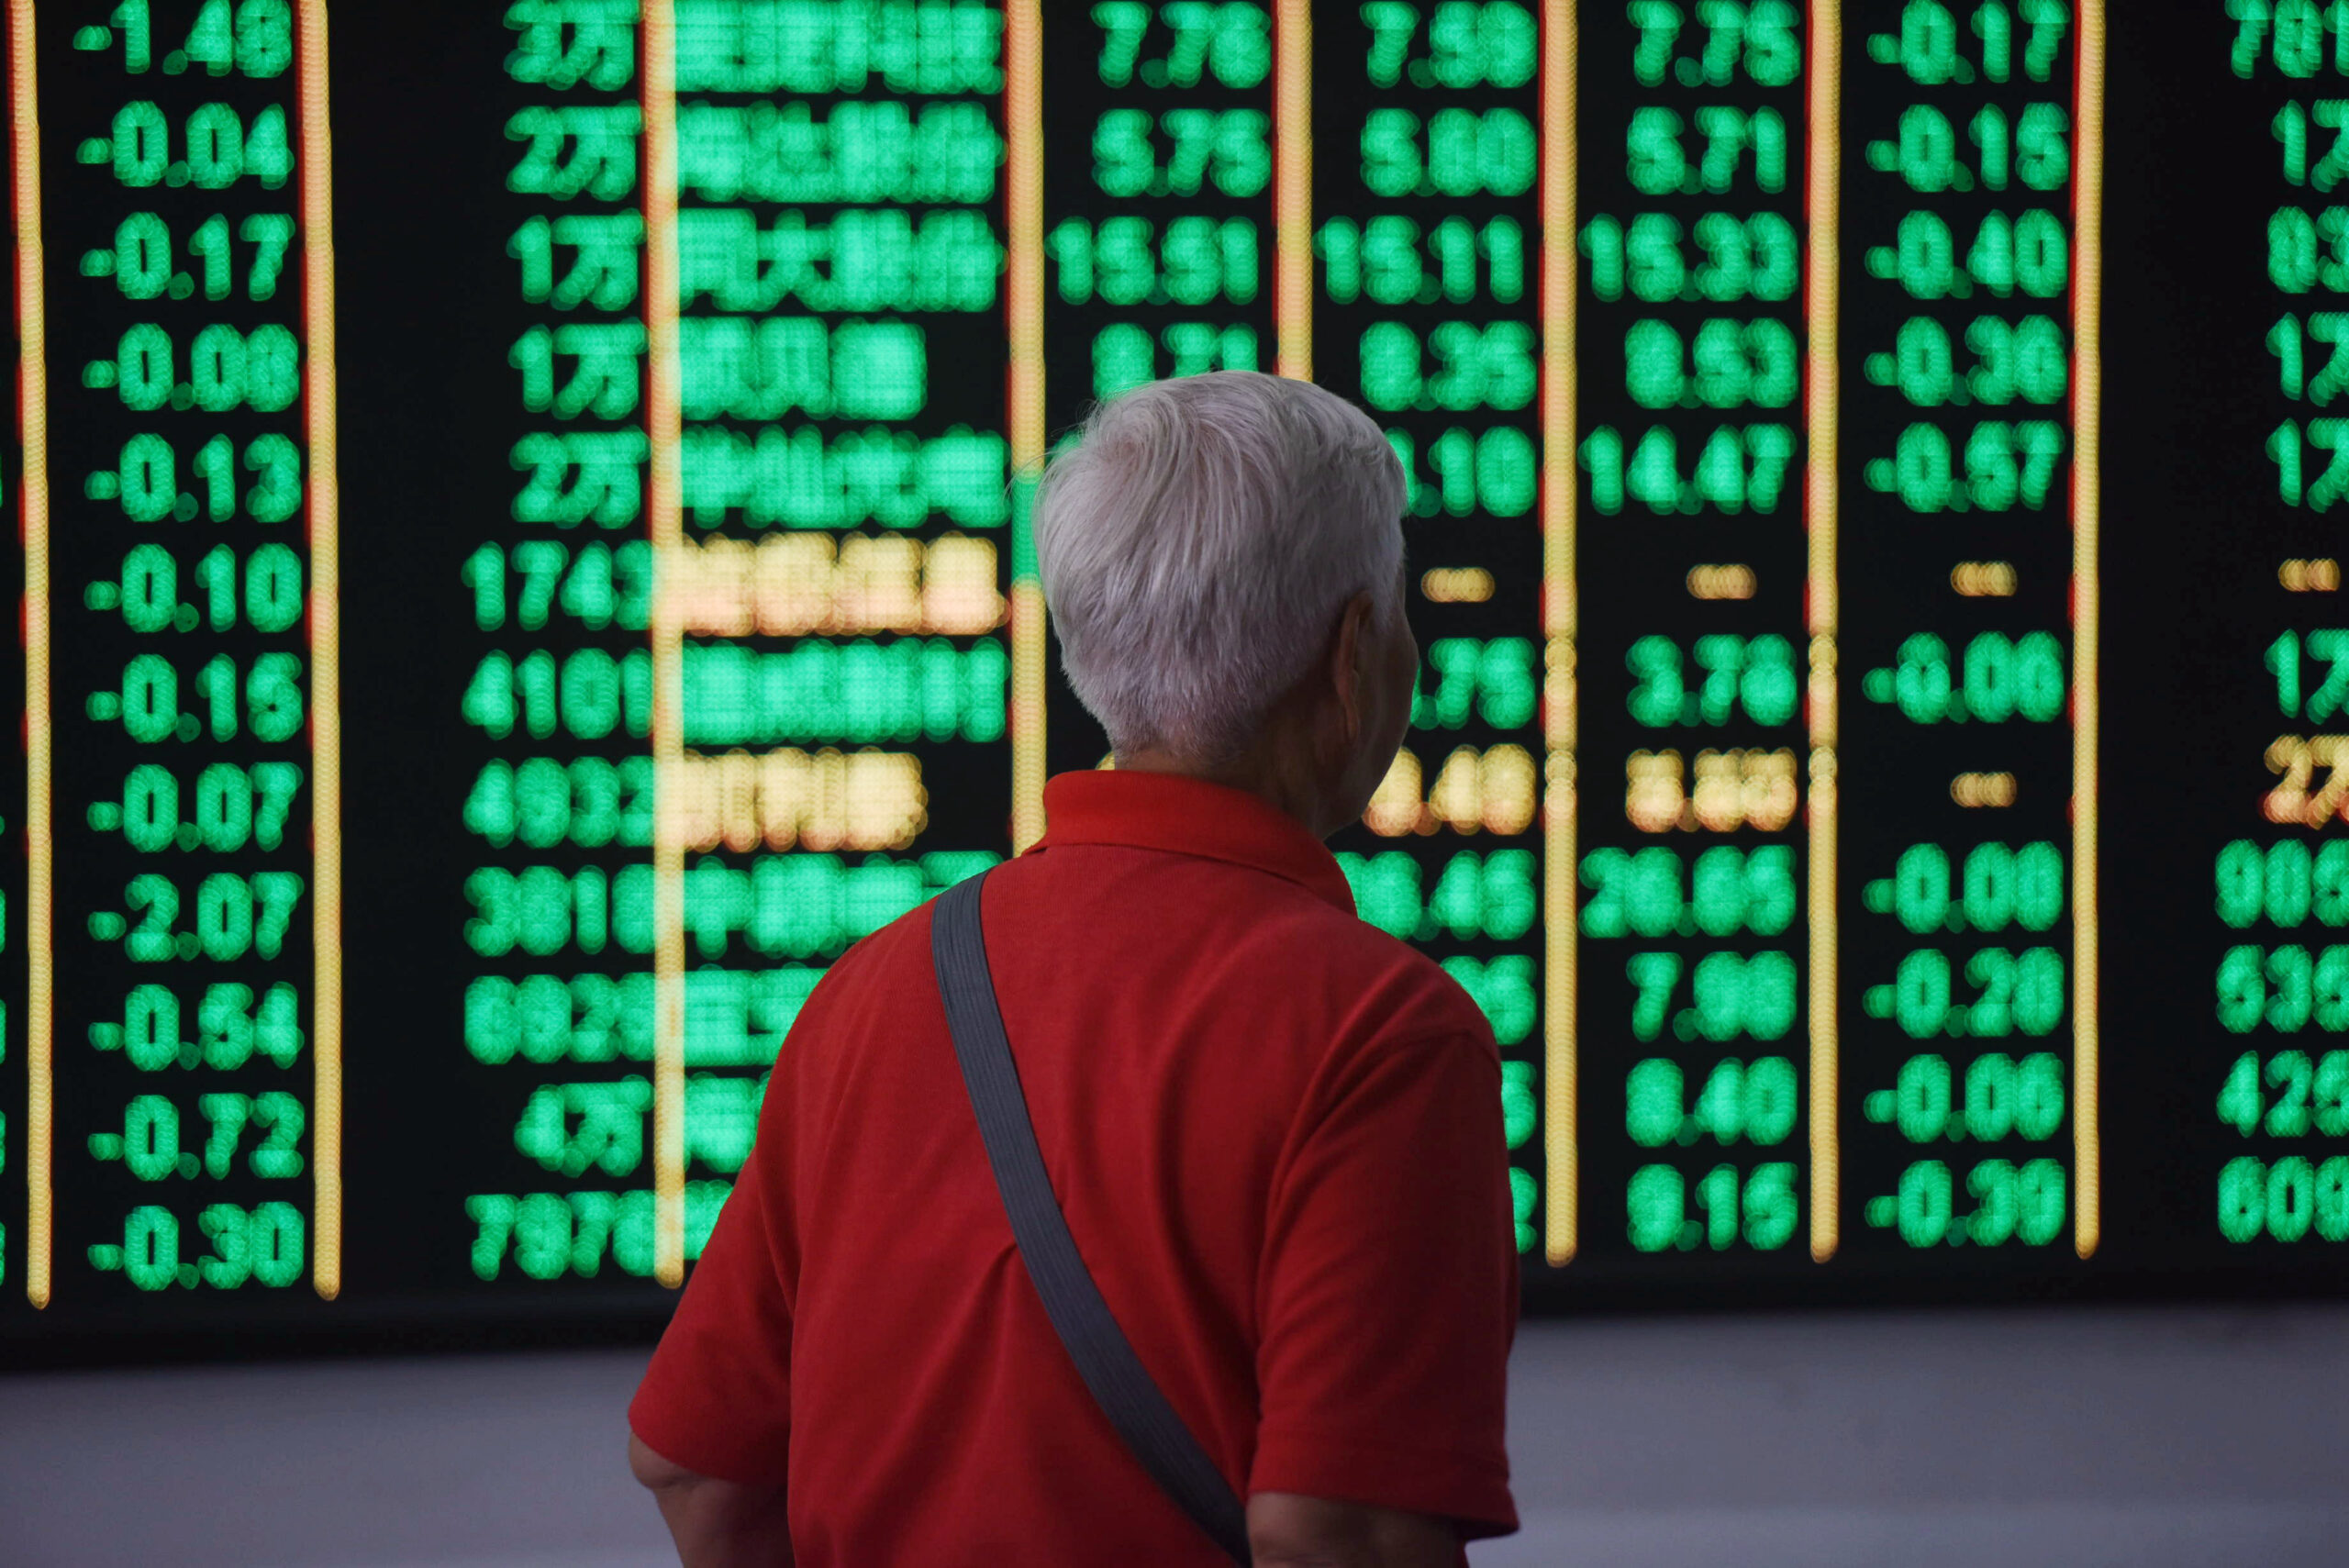
On September 28th, the A-shares of 4554 individual stocks on the mainland experienced a sliding drop, with major stock indices falling to a one-year low. Analysts believe that factors such as the United States planning to implement a procurement ban and institutional portfolio adjustments have led to this downturn in the mainland stock market.
Throughout September 28th, A-shares experienced significant declines, with major indices opening low and continuing to fall. The total trading volume in Shanghai and Shenzhen amounted to 1.7 trillion Chinese Yuan, with all 4554 individual stocks in the market closing on a decline. At the close of the market, the Shanghai Composite Index fell by 1.67% to 3823.62 points; the Shenzhen Component Index dropped by 3.44% to 12858.75 points; and the ChiNext Index plummeted by 4.53% to 3139.82 points.
Various industry sectors displayed a general downward trend. For instance, hash rate hardware stocks declined, with companies like Wind Information and Orise Electronics hitting the limit down; the precious metals sector also trended lower, with Shandong Gold hitting the limit down.
In the Exchange Traded Fund (ETF) market, technology-related varieties took a severe hit. Among them, the communication equipment sector experienced the largest decline on that day, with the Communication ETF of Guotai falling by 7.66%, leading the market on a downward trend. Meanwhile, the Communication ETF of Fuguo dropped by 7.33%, and the ChiNext Hash Rate ETFs of Nanfang and Guangfa both fell by over 7%.
Additionally, artificial intelligence and consumer electronics ETFs also weakened across the board, with the ChiNext Artificial Intelligence ETF and Consumer Electronics ETFs seeing declines of over 5%.
Reports from China Fund News suggested that one of the reasons for the decline was the holiday effect. With only three trading days this week followed by the “Golden Week” national holiday, funds may continue to reduce positions due to risk-hedging needs. At this quarter-end point, institutional portfolio adjustments sparked intense market volatility.
According to Reuters and The Information, there were reports indicating that the Beijing authorities may signal a potential allowance for Chinese companies to purchase the latest semiconductor products from NVIDIA. Given the fierce competition in the local chip industry in China, if companies regain more purchasing options for NVIDIA chips, it could further intensify the pressure faced by local chip manufacturers. This news weakened market sentiment in China, contributing to the stock market decline.
The reports also mentioned that another pressure on A-shares could come from the possibility of the United States issuing a new procurement ban. Four US senators proposed a bill that specifically named Zhongji Xuchuang and Xin Yisheng, aiming to restrict them as suppliers for US government procurement. Following the announcement of this news, the stock prices of these two companies noticeably dropped on the 28th, dragging down related sectors as well.
Billy Leung, an investment strategist at Global X Management, stated that the sanctions proposal against the two Chinese optical communication enterprises could have a certain impact on their profitability, highlighting that technology restrictions and diplomatic negotiations are “running on different tracks.” The trade truce reached by the leaders of China and the US last week was considered “below the market’s initial expectations.”
The reports concluded that the trajectory of the mainland stock market shows that even with a temporary easing of tensions in US-China trade relations, policies related to the technology industry continue to affect investor sentiment. The news of NVIDIA chips potentially re-entering the Chinese market directly impacted local chip stocks. Simultaneously, the proposed new restrictions on Chinese optical communication companies by the US Congress added extra selling pressure to related industries, eventually dragging down the major Chinese stock indices to a one-year low.