
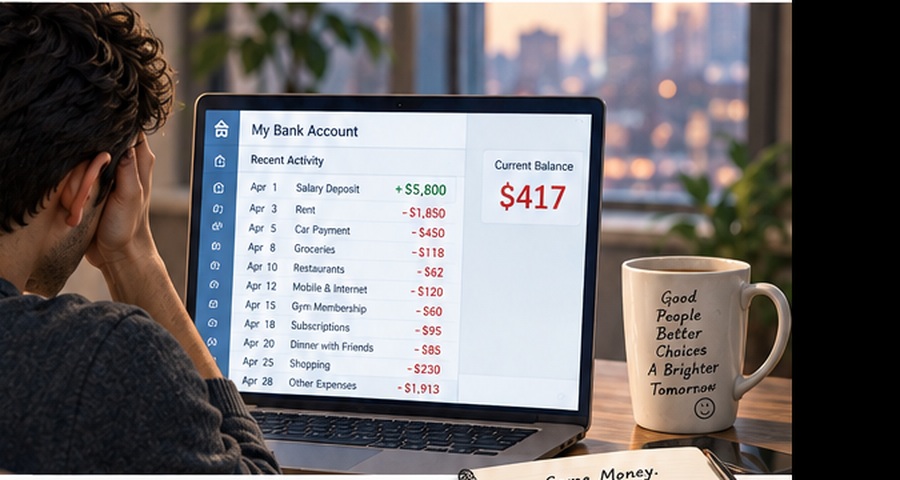
Last Friday, David received a notification of his salary deposit: $5,800. He breathed a sigh of relief. He had been busy with work for the past few months and hadn’t bought anything expensive this month. In theory, there should have been a decent amount of money left in his account.
However, at the end of the month, when he opened his bank account again, the number on the screen made him pause: $417. “Where did the money go?” He hadn’t bought any designer brands, hadn’t suddenly booked a luxurious trip, and hadn’t done any crazy spending he could remember. The money didn’t just disappear in one night. It had quietly slipped away, bit by bit.
David downloaded the bank and credit card statements from the past three months. Rent $1,850, car loan $450, dining and groceries $620, phone and internet $120, gym $60, various subscriptions $95. Plus insurance, gasoline, dining out with friends, occasional purchases, and those seemingly small expenses.
None of them were particularly extravagant. What really surprised him was something else: he had always thought he had a “rough idea” of where the money was being spent, but only when he actually listed every expense did he realize that his memory of life and the reality shown in the bank statements were not exactly the same.
A bank statement is, in fact, a record of life. What we say is important every day and where we actually spend our money are sometimes not the same thing.
Here lies a seemingly simple but easily overlooked distinction: Income is just money flowing in. Wealth is closer to the resources you have left after paying for today’s life and can work for your future.
A monthly salary of $5,800 doesn’t mean you’re increasing your wealth by $5,800 every month. If $5,383 quickly flows out, then what actually remains this month is only $417. This isn’t to say that $5,383 was all “wasted.”
Rent provides housing, food sustains life, a car may get you to work, insurance covers certain risks, a meal with family might be worth its price. The issue is never that spending money is wrong. The real issue is: Did you consciously choose to spend that money, or did it slip away unnoticed?
Many people immediately associate “budgeting” with a list of restrictions: No coffee, no dining out, cancel travel plans, cut out all non-essential expenses. But if you haven’t yet understood where your money is going, rushing to “save” is essentially answering a question you haven’t clarified.
The first step in budgeting is not blaming yourself but observing. What are your fixed expenses? Which expenses repeat every month? Which are occasional? Which expenses do you consider worth it after spending? Which expenses, if you had the choice today, you might not pay for again?
These questions don’t have a one-size-fits-all standard answer. The same $100 could be an unnoticed subscription fee for one person and a significant lesson, a rare family dinner, or a step towards the future for another.
Numbers don’t decide what’s worth it for us. But numbers can help us see for the first time: What choices are we actually making?
David didn’t cancel all subscriptions or immediately set up a strict “saving plan” that night. He did something simpler. He categorized his expenses and looked at the past three months. Because one month might involve unexpected car repairs, a birthday, a trip, or nothing happening at all. Three months are still not perfect but much more reliable than judging his life based on impressions.
He saw a number for the first time that he hadn’t truly seen before: not how much he earns but how much he actually saves each month. This number may be small but it might be closer to the beginning of true wealth than the salary itself.
Income isn’t wealth. Income is just money flowing in. What’s worth noting is how much you have left after paying for life and what that money can do for you in the future.
If you’ve never carefully reviewed your bank and credit card statements, maybe don’t rush to change anything. Just look at three months. Perhaps what you see isn’t just a list of expenses but a version of yourself more honest than memory.
Next up: Your bank statements are actually a record of life—where are the places we are most likely to misjudge ourselves when we truly examine our expenses? David in the text is a fictional character in the “Money and Life” series, used to illustrate the financial choices ordinary people may encounter in real life. The amounts mentioned are for illustration purposes and do not represent any specific individual.