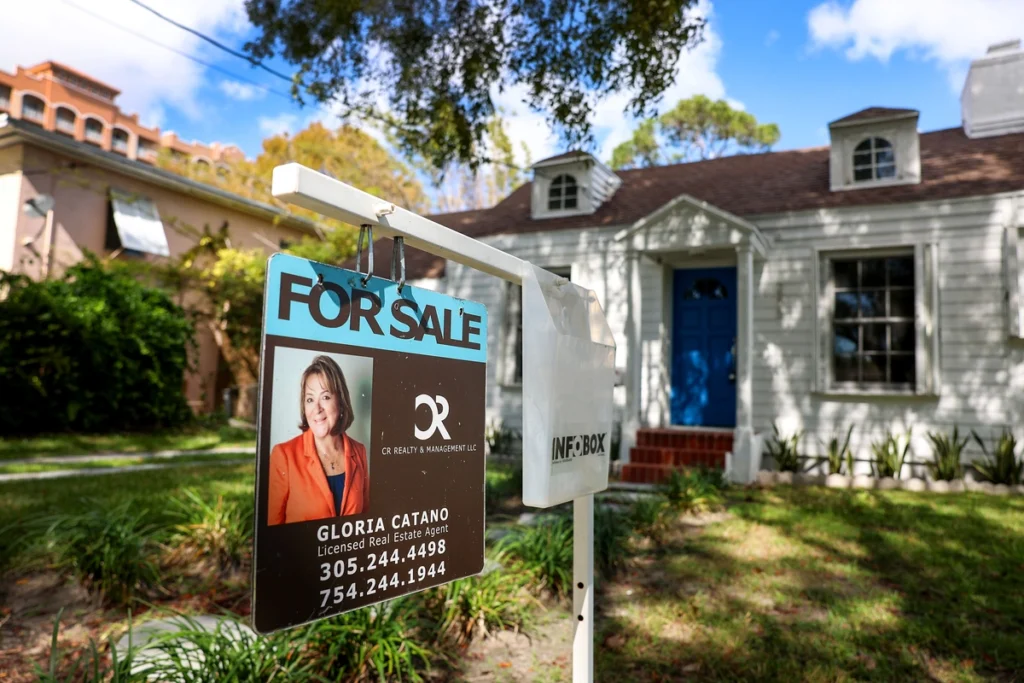
Your offer to purchase a home has been accepted, and the results of the home inspection have come back clear. However, when the home insurance quote arrives, you find that the premium is significantly higher than you had anticipated. This situation may arise due to the past insurance claims history associated with the property.
Before setting home insurance rates, insurance companies consult a report known as the Comprehensive Loss Underwriting Exchange (CLUE). This report outlines any insurance claims made on the property over the past seven years. The records are attached to the house and remain part of its claims history even as ownership changes hands.
In other words, claims made by previous homeowners can potentially lead to increased insurance costs for you as the new owner. Unfortunately, many buyers and homeowners are unaware of the existence of this report.
The CLUE report details the property’s insurance claims over the previous seven years. Insurance companies access this report through a shared industry database to determine both the cost of coverage and whether to approve the insurance application.
This means that if a property has a history of frequent claims, a buyer could be faced with higher premiums and possibly limited coverage in the future.
Although buyers cannot request this report on their own, they can ask the seller to provide a copy or include a clause in the purchase agreement that makes obtaining a “clean report from the seller” a condition of the transaction.
A typical CLUE report includes the types and dates of losses (such as flood or fire), the amount paid by the insurance company for each claim, the claim and policy numbers, and the name of the insurance provider. Importantly, it does not indicate the quality of repairs nor does it reflect unclaimed damages or repairs paid out of pocket by the homeowner.
Claims history is tied to the property itself rather than to the individual seller. However, a buyer’s own insurance history can also influence the insurer’s underwriting decision.
Before providing a quote, insurance companies may review both the previous homeowner’s claims and the buyer’s insurance history.
In addition, some insurers check a database referred to as A-PLUS (Automated Property Loss Underwriting System).
Therefore, even if the CLUE report shows no claims, it does not guarantee that there are no records in other insurance databases.
Some claims recorded in the CLUE report may show a payout amount of zero. For instance, if a claim was made for a burst pipe but was denied, or if a homeowner inquired with their insurer about whether a leak was covered but never filed an official claim, these scenarios might still appear in the report depending on state regulations.
When underwriters review the CLUE report, they are essentially assessing whether the property is likely to incur future losses.
A prior claim for roof damage five years ago carries a different risk than three claims for water damage within the past four years.
Records of claims involving water damage, foundation issues, or roof repairs could indicate that the home may come with costly repair obligations. The more serious the historical claims, the greater the likelihood that the buyer will experience increased premiums, reduced coverage, or possibly even denial of coverage by the insurance company.
Given that standard homeowners insurance typically does not cover flood-related damages, flood claims will not appear as part of the general home insurance claims in the CLUE report.
If the home is located in an area prone to flooding, buyers should inquire about the necessity of purchasing additional flood insurance. Information can be found on the FloodSmart website.
The CLUE report is primarily intended for insurance company use, and only property owners can request to obtain it. Therefore, buyers must seek this report from the seller.
According to U.S. federal law, homeowners are entitled to request a free copy of their own CLUE report once every 12 months, with the reporting agency required to respond within 15 days.
Sellers can also obtain a document known as the Home Seller’s Disclosure Report, which is a version of the CLUE report that does not reveal any personal information about the seller.
If the seller has owned the home for less than seven years, they may not be fully aware of past claim incidents from previous owners, and this report will disclose that information.
Acquiring the CLUE report prior to making an offer allows buyers to take adequate time and make informed decisions based on the findings.
While obtaining a mortgage, lenders usually require borrowers to furnish proof of homeowners insurance.
Monthly homeowner’s insurance premiums are part of the overall housing expenses that also include loan interest, property taxes, and mortgage principal repayments.
If homeowners insurance rates increase, the total monthly housing expense rises accordingly, potentially placing greater strain on family budgets and limiting the home price a buyer can afford.
A blank CLUE report may suggest that no claims have been made on the property in the past; however, it could also mean that the owner has made out-of-pocket repairs, or the insurance company has not reported it to the database. Regardless, this report cannot replace a professional home inspection.
Errors may also exist within the report, such as claim records belonging to other properties being mistakenly associated with this one or a general insurance inquiry being incorrectly noted as a formal claim. Sellers can contest any inaccuracies, and LexisNexis must conduct an investigation free of charge.
Homeowners preparing to sell their properties should consider proactively obtaining their own CLUE report prior to listing.
If inaccuracies are discovered, they can promptly be disputed. Furthermore, homeowners may choose to provide repair records and related receipts to prospective buyers.
In situations where an actual claim could be misleading, homeowners can request that LexisNexis add a brief explanatory note written by them in future reports.
For homeowners who do not currently plan to sell, checking their CLUE reports every one to two years can help them keep track of the recorded information.
The report is not directly accessible to anyone other than the property owner or insurance companies. However, buyers can request a copy from the seller or stipulate it as a condition of their offer. Some sellers may refuse, so buyers should consider inquiring early on about potential insurance quotes to ascertain how insurers assess the property.
The look-back period for CLUE reports is seven years. This means that repair records from ten years ago typically do not appear in a CLUE report. Therefore, buyers should still ask sellers about any significant repairs made to the property in the past and request to see relevant documentation. Professional home inspections can also provide buyers with further insights into the property’s condition.
Yes, in most states, the report may include damages not covered by the insurance company, and some states permit the inclusion of inquiries that were never formally claimed. Please check with the seller regarding specifics. Denied, withdrawn, or amounts below the claim value may not fully represent the property’s status, but they can still affect insurance pricing decisions.
Homeowners can contest information they believe to be incorrect. If you are a buyer and notice a record in the report that seems inaccurate, it is advisable to first ask the seller to verify the situation before deciding whether to proceed with the purchase of the property.